Contents:
- The Problem
- Why Solve It Now
- Step-by-Step Solution
- Step 1: Choose a Payment Processor
- Step 2: Get the Right Hardware
- Step 3: Link Your Business Bank Account
- Step 4: Set Up Fraud Protections
- Step 5: Train Staff on Chargebacks
- Examples
- What the Pros Know
- Troubleshooting
- FAQ
- Do I need a merchant account separate from my processor?
- What happens if a customer disputes a charge?
- Is it legal to charge a card surcharge to cover fees?
- Conclusion
Credit cards have been part of American retail since Bank of America launched the first mass-issued card in 1958, yet setting up card acceptance still confuses a huge share of new business owners nearly seventy years later.
The Problem
Customers increasingly expect to pay by card or tap-to-pay, and businesses that only accept cash lose sales, especially among younger shoppers who rarely carry bills.
Why Solve It Now
Card-only shoppers make up over 40% of in-person retail transactions in 2026. Every day without card acceptance is a measurable share of walked-away customers.
Step-by-Step Solution
Step 1: Choose a Payment Processor
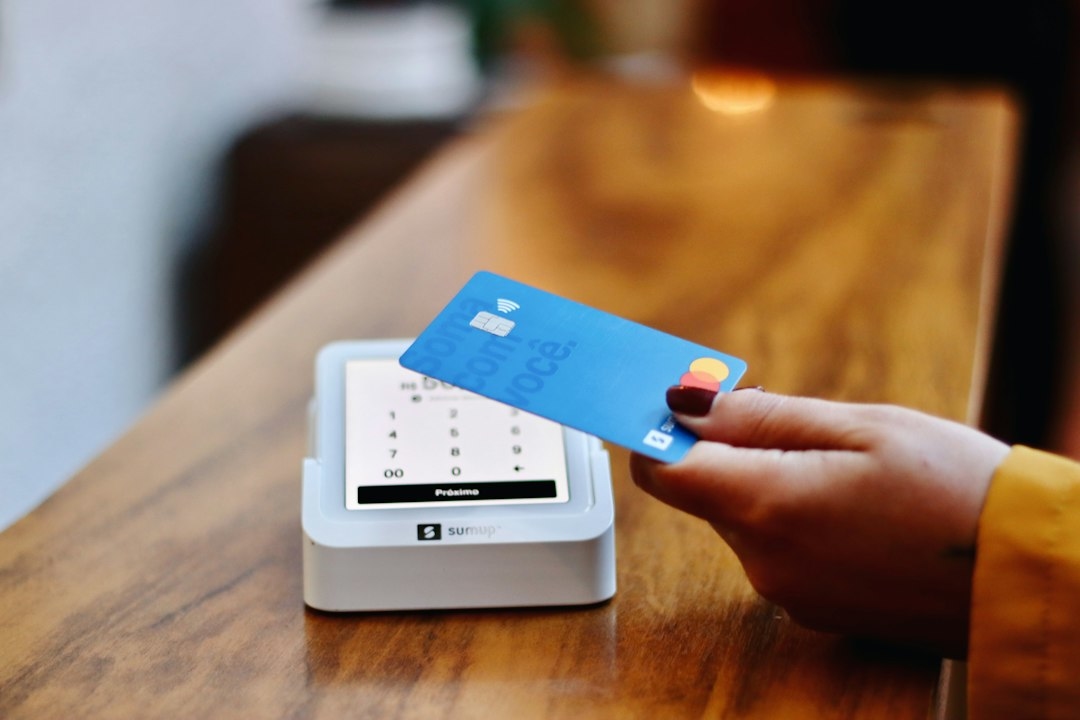
Compare Square, Stripe, and Clover based on your business type. Square suits mobile and in-person sales with flat-rate pricing around 2.6% + $0.10 per tap or swipe. Stripe fits online-first businesses. Clover works well for retail needing inventory integration.
Quick Answer: Sign up with a processor like Square or Stripe, get a card reader or terminal, link your bank account, and you can accept your first card payment within a day.
Step 2: Get the Right Hardware
A basic mobile card reader costs $0-$50. A countertop terminal with a receipt printer runs $200-$600. Choose based on transaction volume, not just upfront cost.
Step 3: Link Your Business Bank Account
Processors deposit funds within 1-2 business days standard, or same-day for an added fee, usually 1% of the transaction.
Step 4: Set Up Fraud Protections
Enable address verification and CVV checks for online transactions, and require chip or tap for in-person sales to shift fraud liability away from your business.
Step 5: Train Staff on Chargebacks
Keep receipts and signed authorizations for every transaction. A missing signature or receipt is the single most common reason merchants lose chargeback disputes.
Examples
A food truck using Square’s mobile reader processes $150 in card sales daily, paying roughly $4 in fees, a small cost against the sales they’d otherwise lose to cash-only limits.
What the Pros Know
“Negotiate your rate once you’re processing over $10,000 monthly,” says Daniel Ferris, a payments consultant. “Most processors have unadvertised volume discounts they’ll only offer if you ask directly.”
Troubleshooting
If deposits are delayed, check that your bank account details were entered correctly during signup, the most common cause of holds. If fees seem high, calculate your effective rate including any monthly minimums, not just the advertised per-swipe percentage.
FAQ
Do I need a merchant account separate from my processor?
Most modern processors like Square and Stripe bundle the merchant account into their service, so you don’t need to apply separately.
What happens if a customer disputes a charge?
The processor notifies you, gives you a deadline to submit evidence like receipts or delivery confirmation, and then rules on the dispute, typically within 30-60 days.
Is it legal to charge a card surcharge to cover fees?
In most states yes, within limits, but a handful of states restrict or ban surcharging entirely, so check your specific state’s rules first.
Conclusion
Accepting cards is no longer optional for most small businesses. Pick a processor that matches your sales pattern, get the hardware that fits your volume, and revisit your rate annually as your transaction volume grows, since loyalty rarely earns you a better deal without asking for one directly.